The Invoice Was Sent. Why Is Cash Still Waiting?
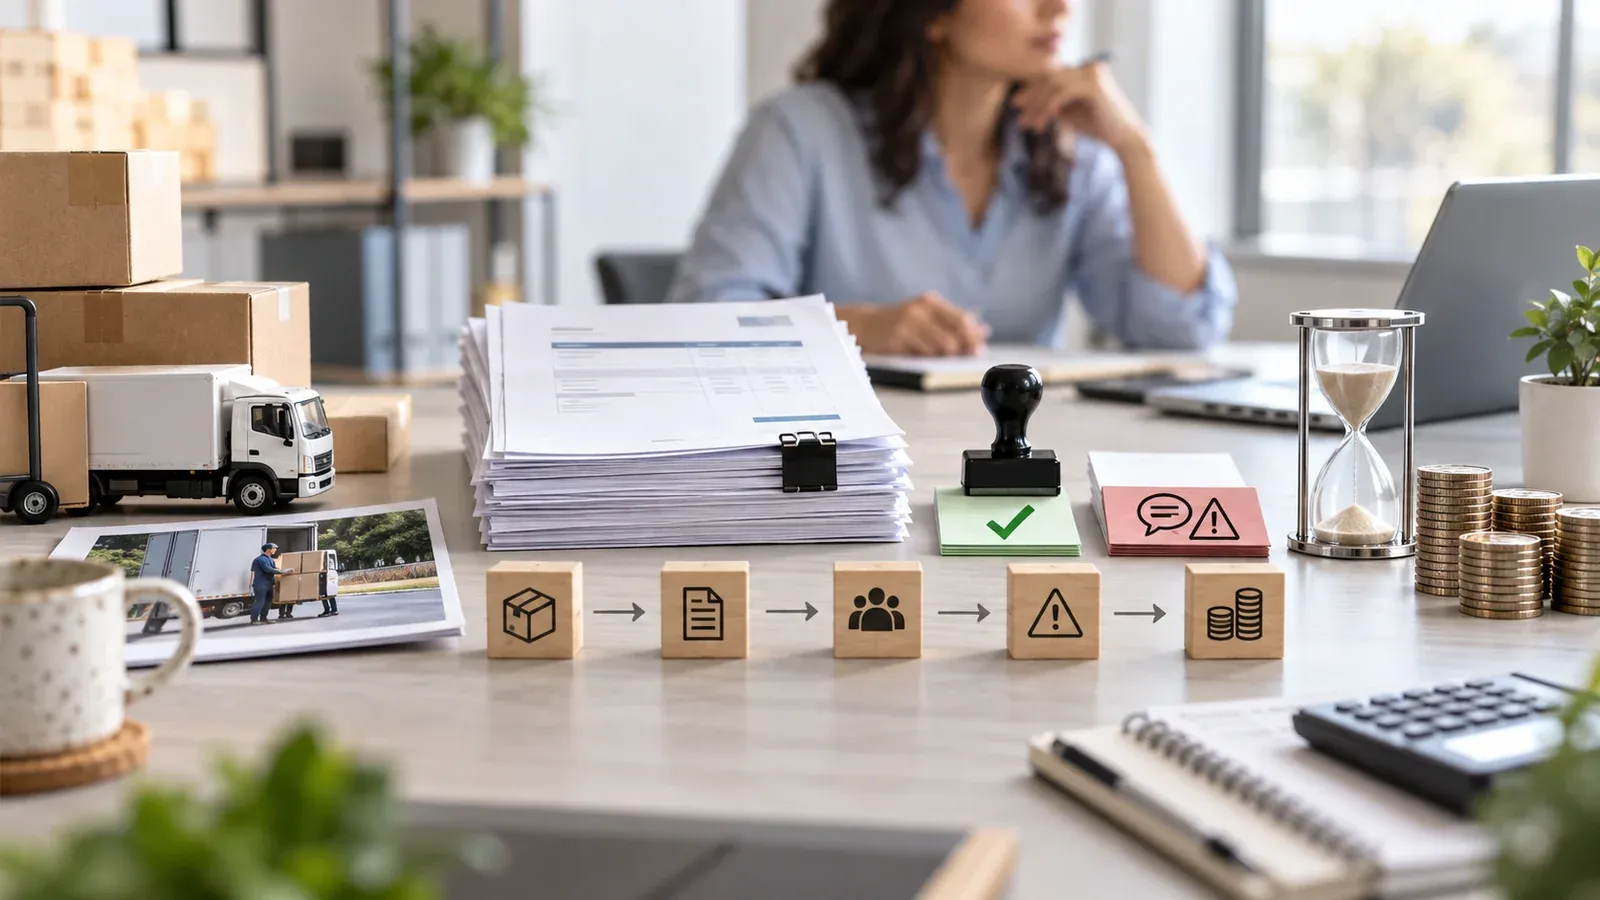
Cash delay often begins long before accounts receivable—inside order accuracy, shipment proof, pricing logic and dispute handling.
The short answer
Cash delay often begins before finance touches the invoice. The root cause may sit in order accuracy, shipment proof, pricing control, customer acceptance, dispute ownership or credit-release behavior. By the time the invoice ages, the real operational problem may be days or weeks old.
For Epicor users, improving order-to-cash usually means connecting delivery evidence and dispute workflow more tightly to the commercial record.
Do not start with collections only
Collections matter, but asking finance to chase harder cannot solve an upstream documentation problem.
Review whether late cash is mainly driven by:
- invoice sent to the wrong contact or in the wrong format;
- shipment proof incomplete or late;
- quantity or price mismatch;
- missing customer acceptance or service confirmation;
- credit note/dispute loop unresolved;
- customer query with no single owner.
Each pattern requires a different response.
Make shipment proof usable
In many organizations, the invoice can technically be raised before the evidence needed for collection is complete. That creates a dangerous illusion of progress.
Good order-to-cash control asks:
- what proves delivery or completion;
- when that proof is available;
- whether it is linked to the invoice process;
- whether customer-specific billing rules are visible before shipment.
If the answer is weak, finance inherits an avoidable collection problem.
Separate dispute types
Not all late invoices are alike. Distinguish:
- administrative issues;
- pricing issues;
- quantity issues;
- delivery-evidence issues;
- quality/service issues;
- customer payment-behavior issues.
Then decide who owns each type and what response time is expected.
This prevents disputes from sitting invisibly inside aging buckets.
Give operations visibility into cash blockers
A late invoice is not always a finance-only issue. Production, warehouse, logistics, service and customer service may hold pieces of the answer.
Examples:
- warehouse knows proof-of-delivery was never returned;
- customer service knows the customer challenged the price;
- production knows a replacement shipment is still open;
- sales knows the customer requested consolidated billing.
Order-to-cash improves when those facts surface early.
Where Epicor and ACC fit
Epicor can provide the transactional backbone linking order, shipment and invoicing. Management improvement comes from clarifying evidence, workflow and ownership.
ACC can help where the business needs to tighten practical operational steps—particularly in multi-country operations, Asia execution or warehouse-linked proof-of-shipment processes—without turning order-to-cash into a purely accounting conversation.
Run a late-cash fact review
Take ten overdue invoices and answer for each:
- was the underlying delivery/service event complete;
- was the invoice technically correct;
- was all required proof available;
- did the customer raise a dispute;
- who owned resolution;
- what would have prevented the delay upstream.
Then quantify the patterns. This often turns a vague collections concern into a focused improvement agenda.
Bring aging review closer to root cause
Traditional aging reports are useful, but they often hide the operational reason for delay. Add a parallel view that shows overdue value by blocker type: missing proof, pricing dispute, quantity dispute, service acceptance, customer query or payment behaviour.
This lets management see which delays are solvable through process design and which are true customer-credit issues.
Metrics that matter
Useful order-to-cash indicators include:
- invoice-to-cash days by customer segment;
- overdue value with known blocker versus unknown blocker;
- dispute resolution cycle time;
- percentage of invoices raised with complete supporting evidence;
- credit-note value as a proportion of invoiced value.
These measures help turn AR meetings into action-oriented improvement reviews.
Make aging review operationally meaningful
Traditional aging reports are necessary, but they rarely explain why cash is delayed. Add a parallel view that classifies overdue value by blocker type: missing proof, pricing dispute, quantity dispute, service acceptance, customer query or payment-behaviour issue.
This allows management to separate true credit risk from process-driven delay. It also shows where upstream operational correction will have more value than additional collection effort.
Design ownership around dispute categories
Different blockers require different owners. Pricing queries may belong with customer service or sales operations. Missing proof may belong with warehouse or logistics. Service acceptance issues may belong with field teams. Without explicit ownership, finance sees the symptom but cannot drive resolution efficiently.
A simple response matrix—blocker type, owner, response expectation and escalation point—often improves the order-to-cash chain more than a purely financial intervention.
Useful order-to-cash measures
Useful indicators include:
- invoice-to-cash days by customer segment;
- overdue value with known blocker versus unknown blocker;
- dispute resolution cycle time;
- percentage of invoices raised with complete supporting evidence;
- credit-note value as a proportion of invoiced value.
These make the conversation more actionable and less anecdotal.
Part of the wider Epicor coordination series
This cluster belongs to the larger pillar Epicor Connects the Business. Where Does Coordination Still Break Down?. It shows that late cash is often the financial memory of earlier coordination failures elsewhere in the business.
Find the first avoidable delay point
When studying overdue invoices, it helps to identify the first avoidable delay in the chain. Was it the missing delivery proof? An unresolved price difference? A delayed customer acceptance? A shipment that should not have been invoiced yet? This approach is powerful because it stops the business from arguing at the end of the process and instead improves the earliest preventable point.
Over time, that reduces both aging and management frustration.
Use customer-specific rules deliberately
Many businesses serve customers with different billing requirements, acceptance rules and dispute habits. Those differences should be understood before the invoice is raised, not after it becomes overdue. Capturing such rules clearly reduces avoidable friction and helps operations support finance more effectively.
Use a weekly blocker review
A short weekly review of the highest-value blocked invoices can help the business act earlier. The discussion should focus on blocker type, owner, next action and whether the issue is repeating across multiple customers or sites. This gives operations and finance a shared rhythm for protecting cash.
Keep the customer communication loop clear
Many disputes linger simply because the customer does not know who is answering or when the next update will arrive. A clear communication owner and response expectation can shorten cycle time significantly.
A simple management checklist
In an overdue-invoice review, ask: what event should have enabled payment, what blocker is now stopping it, who owns resolution, what customer communication is active, and what upstream change would have prevented the delay? These questions help turn an aging list into an improvement tool.
Treat evidence quality as part of invoicing quality
Invoicing quality is not only about price and quantity accuracy. It also includes the quality of evidence attached to the commercial event. When proof of delivery, service confirmation, acceptance or dispute context is weak, the invoice may be technically correct but commercially fragile.
That distinction helps management improve the real collectability of revenue rather than only the speed of invoice creation.
Improvement goal
The objective is not only faster chasing. It is a cleaner chain from delivery evidence to collectible revenue.
Keep blocker ownership visible
A blocker that belongs to everyone usually belongs to no one. Visible ownership shortens resolution time and reduces aging drift.
Good practice
Short, regular cross-functional reviews usually improve cash faster than sporadic escalation.
Frequently asked questions
Is this just about AR discipline?
No. AR discipline matters, but many late-cash causes are created upstream.
Should invoices wait for every piece of evidence?
That depends on customer and process design, but the rule should be explicit. Hidden assumptions create aging.
How can operations help?
By making delivery proof, exception handling and customer communication more timely and visible.
Is order-to-cash mainly a finance topic in Epicor?
It is a finance-led topic with strong operational dependencies.
Where does ACC fit?
ACC can support the operating design and execution disciplines that make the order-to-cash chain more complete and reliable.
Cash waits when ownership is fragmented
The fastest way to improve cash is often to reduce the number of unresolved handoffs between shipment, proof, invoice and dispute resolution.