

The Factory Hit the Quantity. Why Did the Order Still Lose Margin?
Shipped quantity does not explain profitability. Actual fabric use, labor efficiency, overtime, rework, subcontracting and logistics can move the margin even when output targets are met.
The short answer
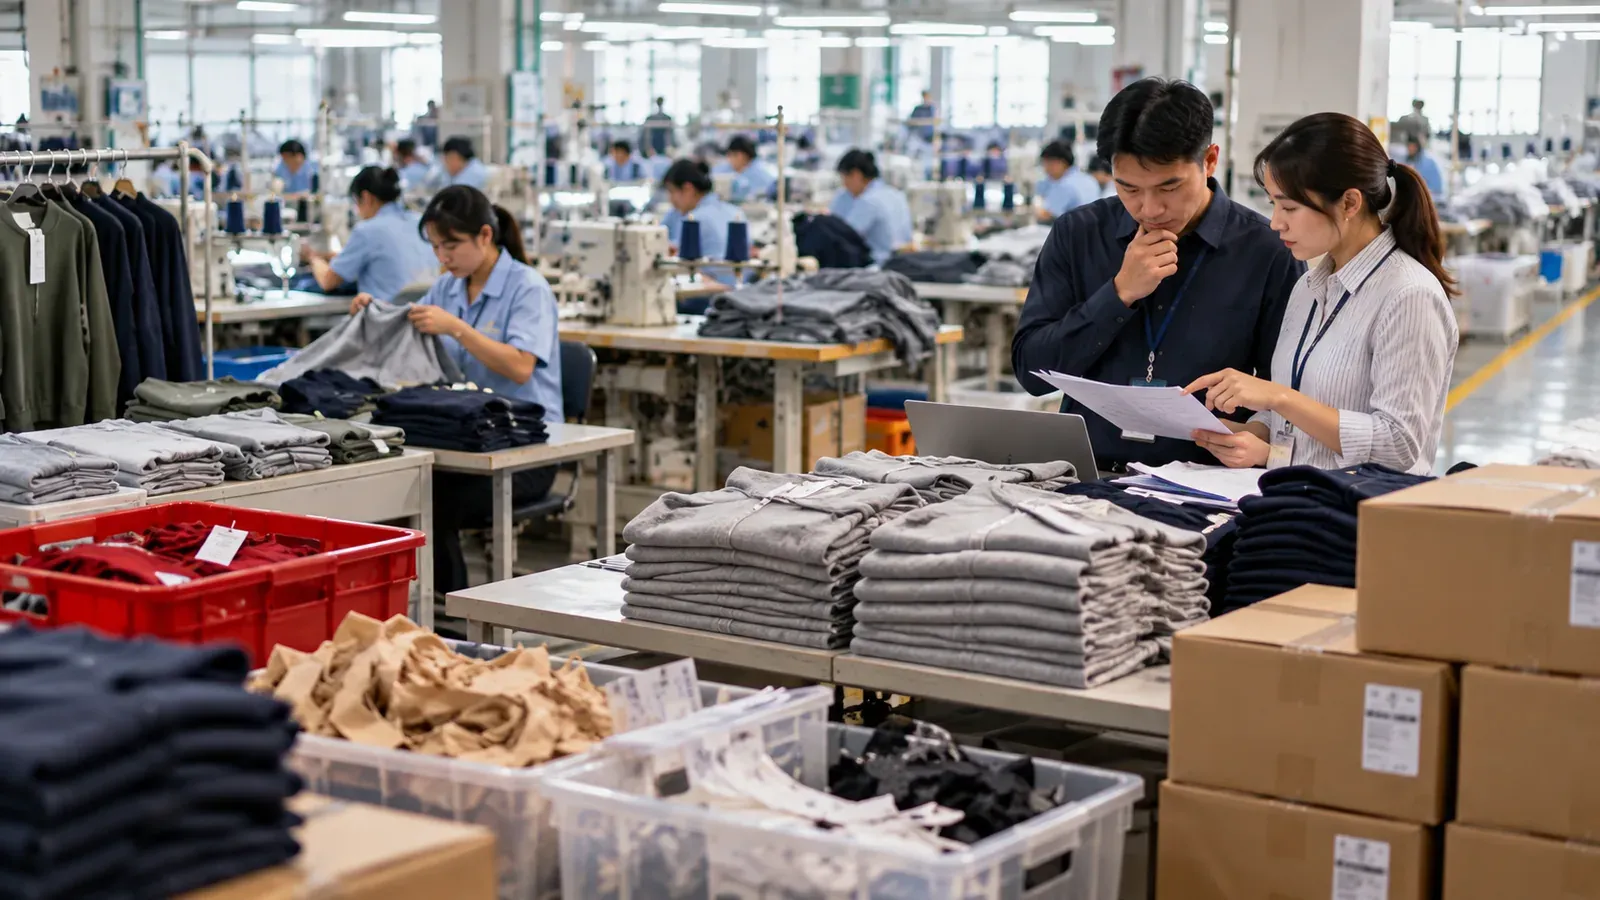
A garment factory can hit the ordered quantity and still lose margin because quantity is only one dimension of performance. The order may have consumed more fabric than planned, required more labor minutes, used overtime, created rework, needed subcontracting, generated residual material or shipped in a more expensive way than the quote assumed.
The right profitability question is therefore not “Did we make the pieces?” but “What resources and exceptions did we consume to make and ship them?” Actual-cost control connects production evidence to the same order baseline used at quotation.
The wider margin story is explored in From Confirmed Order to Final Margin: Where Does Garment Profitability Drift?: actual factory performance gradually replaces the assumptions used at quotation.
The factory can hit quantity and still lose the economics of the order
Operational dashboards often celebrate attainment: target quantity achieved, shipment on time, line output complete. Those measures matter, but they do not explain whether the order was produced economically.
Consider two orders that each ship 20,000 pieces. The first runs close to planned efficiency with normal material yield and one shipment. The second needs repeated line balancing, weekend overtime, additional fabric, repair work and a split shipment. Quantity is identical. Margin is not.
If management stops at output, cost erosion becomes visible only after finance closes the month.
The quote is the reference point, not a number to forget after confirmation.
A useful actual-cost comparison requires a clear baseline. The original estimate should identify the main economic drivers of the order, such as:
- material consumption and purchase price;
- CM or expected labor content;
- expected efficiency or production minutes;
- planned subcontracting;
- packaging and testing;
- factory allocation;
- shipment method and freight responsibility;
- currency assumptions where relevant.
The objective is not to make the quote perfect. It is to know which assumptions mattered so actual performance can later be explained.
Material margin can move even when purchase price looks normal
Material cost can move because the supplier charged more, but in apparel the larger issue is often usage.
Fabric yield can change with width, shrinkage, shade grouping, marker efficiency, defects and cutting loss. Replacement panels and rework can consume additional material. Color-size mix can create different consumption from the original estimate. Residual rolls may remain after the order closes.
Management should separate at least three questions:
1. Did the material cost per unit differ from expectation?
2. Did actual consumption per garment differ?
3. Did the order create residual or unusable material that should be attributed economically?
Without that distinction, “material variance” is too broad to support action.
Labour variance is useful only when it explains what happened on the floor.
An order can lose labor margin through:
- lower-than-expected learning performance;
- frequent style changeovers;
- poor line balance;
- absenteeism or skill gaps;
- machine downtime;
- material feeding delays;
- quality rework;
- overtime premiums;
- small lots that never reach stable efficiency.
Actual labor cost therefore needs both financial and operational evidence. A payroll total alone says the factory spent money; the production context explains why.
Overtime can save the shipment while weakening the margin.
Overtime is sometimes the correct decision. A late buyer approval or material delay may leave no other practical recovery option. The problem is when overtime protects the delivery date but its cost is invisible in order profitability.
Management should be able to distinguish:
- planned overtime included in the quote;
- recovery overtime caused by internal inefficiency;
- recovery overtime caused by buyer change or late approval;
- overtime caused by material or supplier delay;
- overtime caused by quality or rework.
These categories support different management actions and different commercial conversations.
Rework is production effort the customer never buys twice
Repair and rework are often treated as shopfloor activity rather than order cost. That hides one of the clearest links between quality and profitability.
A repair operation may consume labor, thread, trims, replacement panels, inspection time and queue capacity. It may also force the line to work around incomplete bundles, reducing flow efficiency for other work.
If all of that is absorbed into general factory overhead, management sees a weaker factory result but cannot identify which orders or styles caused it.
Quality Passed at Final Inspection. Where Did the Cost of Rework Go? looks more closely at how rework can consume capacity and margin long before final inspection appears clean.
Subcontracting can be expensive and still be the right decision.
Subcontracting creates a direct external charge, but management should also ask what internal constraint it solved.
A subcontracting decision may avoid overtime, protect a delivery penalty, access a specialist process or free a critical line. A fair evaluation compares the external cost with the alternative scenario rather than labeling all subcontracting as negative variance.
The control requirement is attribution: the charge, quantity, operation and quality outcome must link back to the customer order.
The margin can keep moving after the garments leave production.
Split shipments, premium freight, additional documentation, storage and last-minute route changes can materially affect an order after production output is complete.
This is why shipment date and profitability close date should not be treated as the same event.
A provisional margin at shipment can be useful, but it should be labeled as provisional until major logistics and supplier costs are posted.
A margin number matters less than the story of how it moved
The most useful order review explains the movement from quoted margin to actual margin.
A simple bridge might show:
- quoted margin;
- buyer-change impact;
- material price impact;
- material usage/yield impact;
- labor efficiency impact;
- overtime;
- quality/rework;
- subcontracting;
- logistics;
- other close adjustments;
- final margin.
This is more actionable than a single percentage because each bridge item points to a process and owner.
The warning signs appear before the final P&L.
Useful order-level measures include:
- actual versus planned fabric consumption;
- actual labor minutes versus expected minutes;
- overtime hours and premium by order;
- rework hours and material replacement cost;
- subcontracting cost per operation;
- freight and shipment variance;
- residual material value after close;
- elapsed time from production completion to actual-cost availability;
- percentage of margin variance with an assigned root cause.
Management should prioritize explanation quality over false precision. A margin that is 0.2 percentage points more accurate but three weeks late is less useful than a timely estimate with clearly labeled confidence.
Where Epicor Venus connects factory reality with order margin
Epicor provides the enterprise-grade ERP foundation for purchasing, inventory, commitments, finance and governance. Epicor Venus adds the garment-specific style, BOM, costing, line, production and delivery context needed to explain why the order is moving away from its original commercial assumptions.
The value is not another end-of-month margin report. It is the ability to connect material usage, rework, overtime, subcontracting and shipment decisions back to the same customer order while management can still intervene. ACC helps garment manufacturers shape those controls around Epicor and Epicor Venus so commercial and factory teams are reading the same order story. Explore Epicor Venus for garment and apparel manufacturing.
Margin control becomes valuable while the order can still change
Waiting for final actual cost creates a control gap. Many of the strongest margin signals are available while the order is still running.
For example, fabric usage can be compared with expected consumption after the first meaningful cutting lots. Labor efficiency can be reviewed after the line has passed its learning period. Rework trends can be visible after early quality checkpoints. Overtime and subcontracting decisions are known before shipment. These are not final financial results, but together they can create a useful forecast actual.
A forecast actual should be updated only when the evidence is strong enough to matter. Constantly changing the margin for tiny fluctuations can create noise. The purpose is to identify material drift early enough for management to respond.
Useful triggers include a consumption variance above tolerance, sustained efficiency below plan, repeated overtime, significant rework growth, emergency subcontracting or an unplanned shipment split. Each trigger should prompt a question: can the cost still be reduced, can the buyer absorb part of it, or should the business consciously accept the lower margin?
This turns actual costing from a month-end explanation into an operational feedback mechanism.
Frequently asked questions
Should actual cost be available before shipment?
A useful estimate should. Some final supplier, freight or accounting items will arrive later, but material usage, labor, overtime, rework and subcontracting can usually be estimated during execution.
Is line efficiency enough to explain labor variance?
No. Efficiency is important, but changeovers, downtime, rework, feeding delays and overtime premiums can also affect labor economics.
Should residual fabric be charged to the order?
That depends on whether it can be reused economically. The key is to make the decision explicit rather than leaving residual stock outside the profitability discussion.
How often should order margin be recalculated?
At meaningful control points: after major order changes, during execution when material variances emerge, at shipment, and at financial close.
What is the first report to build?
A quoted-to-actual margin bridge for recently shipped orders. It quickly reveals which variance categories are missing or arriving too late.