

The Quote Won the Job. Will the Job Still Make the Margin You Expected?
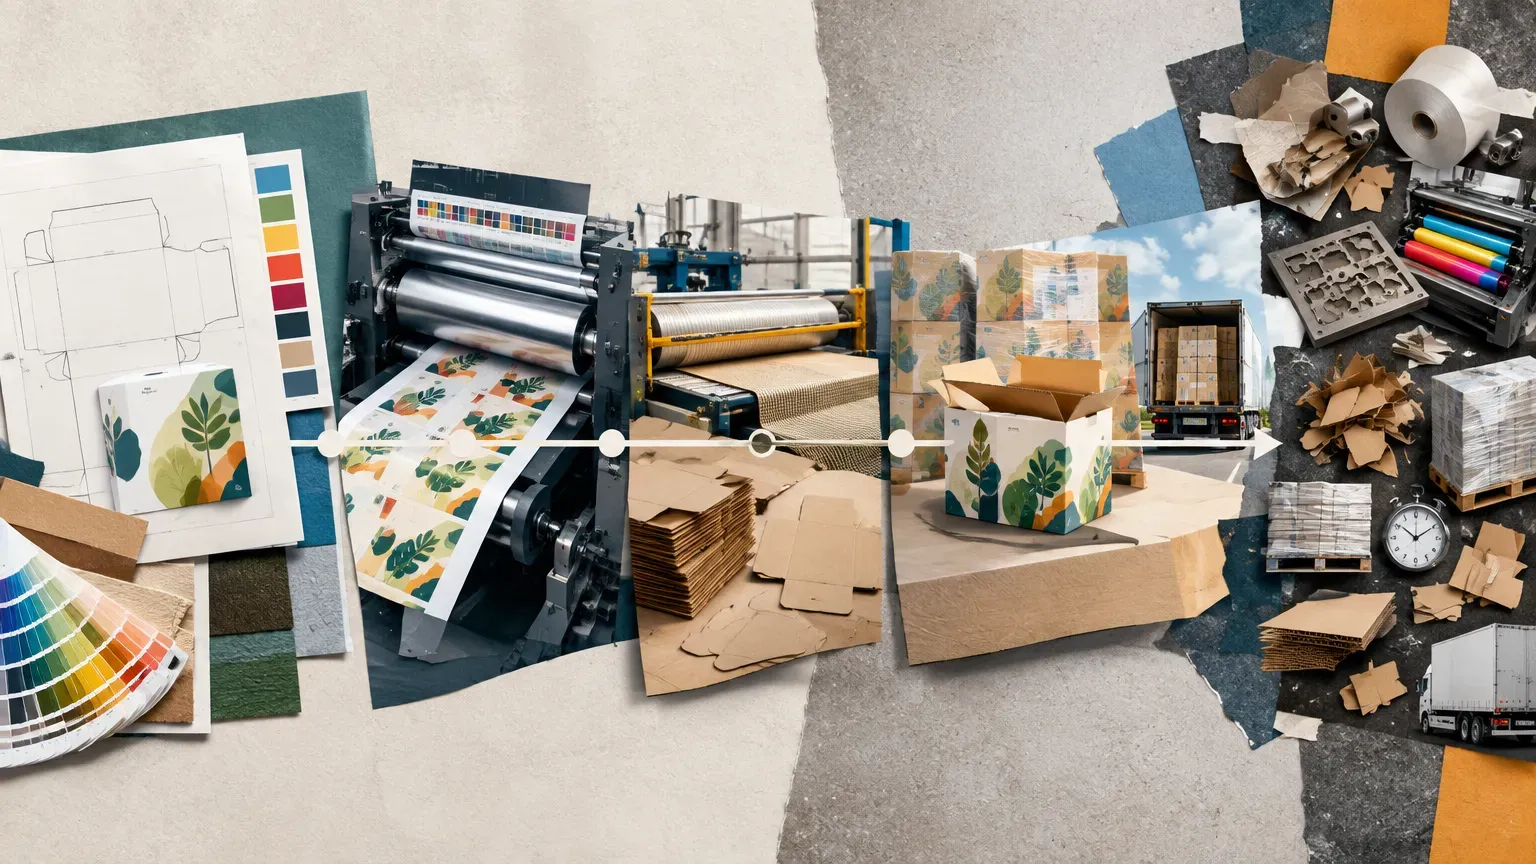
Printing and packaging profitability is decided long before the invoice. A reliable estimate connects specification, material yield, makeready, run speed, tooling, finishing, subcontracting, waste and delivery assumptions to the actual job that production will execute.
The short answer
A printing or packaging estimate is reliable only when it describes the job production will actually execute. Selling price can look attractive at quotation while margin is quietly exposed by material yield, makeready, press speed, finishing sequence, subcontract minimums, spoilage, packing, freight or customer changes that were not represented accurately in the estimate.
The useful management discipline is therefore not simply “estimate more carefully.” It is to create a closed loop from specification → estimate → production route → actual consumption → final job cost → estimating feedback.
Jupiter can support that job-based operating model by keeping commercial assumptions connected to the same job information used by planning, production, materials, finishing and costing. The aim is not perfect prediction. It is to make assumptions visible enough that the business can learn systematically when actual economics differ.
Margin begins with the job definition
Before any rate is applied, the estimator needs to know what is actually being sold.
Printing and packaging work combines many variables:
- finished dimensions;
- quantity and delivery split;
- artwork or number of versions;
- colors;
- substrate;
- grain or material orientation;
- print method;
- proofing;
- coating or lamination;
- foil, embossing or other special effects;
- die-cutting, folding or gluing;
- inspection;
- packing;
- freight;
- customer-specific handling.
A missing assumption can be more damaging than a slightly inaccurate machine rate.
That is why estimating quality begins with specification quality.
The specification can look complete and still be commercially incomplete
A customer may provide dimensions, artwork and quantity.
The estimator may still need to decide how the job will be imposed, which sheet or web size is practical, how much makeready is needed, whether finishing must run in multiple passes, what packing configuration is required and whether delivery needs special handling.
These operational assumptions often determine the difference between quoted and actual margin.
The Specification Looks Complete. What Is Your Estimate Still Missing? explores how to expose those hidden requirements before price is committed.
Material is usually more than finished quantity
A carton order for 100,000 units does not require material for exactly 100,000 perfect units.
The estimate may need to cover:
- trim;
- imposition loss;
- grain constraint;
- makeready sheets;
- process spoilage;
- inspection samples;
- finishing waste;
- supplier minimum quantity;
- reel or sheet remnants;
- overs.
The right allowance depends on process and experience.
A generic waste percentage may be convenient but can hide substantial differences between job types.
How Much Paper or Board Will the Job Really Consume? focuses on turning material yield into a more controlled costing assumption.
Makeready is an event, not just a percentage
Setup cost is often treated as one line in the estimate.
The actual production route may create several setup events.
A job may be split across machines, produced in two delivery waves, restarted after a customer hold, or require separate finishing setups.
Even within one process, additional color, plate, substrate or tool changes can alter the setup requirement.
Makeready Was Budgeted Once. Why Did the Job Need It Three Times? looks at how to estimate the real setup pattern rather than one ideal run.
Press economics do not equal job economics
Printing is only one part of many packaging jobs.
A profitable press run can be followed by expensive lamination, die-cutting, foil, handwork, gluing, inspection or subcontract processing.
Outside suppliers may impose minimum charges, transport, tooling or expedite premiums.
Downstream yield can also be lower than press yield.
The Press Rate Looks Profitable. What Happens When Finishing and Outsourcing Are Added? covers the route-level economics that can disappear when estimating focuses too heavily on press time.
Use rates carefully
Machine and labour rates matter, but they should not become a false source of precision.
A rate can be calculated perfectly and still produce a weak estimate if the expected hours are wrong.
Likewise, run-speed assumptions can create major variance.
A press capable of a high rated speed may run slower for a specific substrate, color requirement, job length or quality tolerance.
The estimate should use realistic job conditions rather than headline equipment capability.
Separate standard assumptions from job-specific exceptions
A strong estimating model does not require every job to be built from zero.
Standard assumptions are useful for:
- common material waste;
- normal setup time;
- typical press speeds;
- standard finishing rates;
- packing patterns;
- usual freight or handling rules.
But the estimator should know when the job is outside that standard.
Examples include unusual board, very short runs, multiple versions, tight color tolerance, difficult finishing or compressed delivery.
The exception should be visible because it is where margin risk usually increases.
Quote revision should preserve history
If the customer changes the job before order acceptance, the estimate changes.
Keep enough revision history to know what changed between versions.
A lower quantity may worsen unit economics. A new finish may add subcontract cost. A new dimension may reduce imposition efficiency. A faster delivery requirement may require overtime or premium freight.
Preserving the change helps the business understand why the final price differs from an earlier quote.
It also supports the change-control discipline used later after order acceptance.
Capture the route the estimate assumed
The estimate should identify the expected production route.
If actual production uses a different press, extra process, alternate finishing supplier or additional handwork, the cost comparison becomes meaningful only if the baseline route is known.
Without that baseline, actual variance is just a number.
With it, management can ask whether the estimator was wrong, production deviated, or the job itself changed.
Actual cost should feed the next estimate
The estimate does not become more accurate simply because actual costs are available.
Someone has to interpret the difference.
Actual Cost Is Higher Than Estimate. Which Assumption Was Wrong? focuses on separating material, time, waste, rate, routing and scope variance.
The feedback should be selective.
One unusual breakdown should not automatically become the new standard. Repeated evidence across similar jobs is stronger.
Repeat jobs need revalidation
A repeat order creates an obvious opportunity to reuse prior information.
It also creates complacency risk.
Material prices change. Run length changes. Equipment changes. Tooling wears. Freight changes. The previous job may have contained hidden overtime or excessive waste.
The Customer Says, “It’s Just a Repeat Job.” Should the Price Still Be the Same? examines how to use history without copying old economics blindly.
Build an estimating assumption library
A practical estimating system can maintain controlled assumptions by relevant category.
Examples include:
- press setup time;
- normal run speed by material/job family;
- spoilage allowance;
- finishing setup;
- subcontract minimums;
- packing productivity;
- freight rules.
Each assumption should have an owner and review trigger.
The library should not become a huge theoretical model.
Focus on assumptions that materially affect selling price or margin.
Use actual production evidence to tune standards
The best standards usually come from controlled history.
Compare similar jobs and ask:
- What setup time repeats?
- What run speed is sustainable?
- What material yield is normal?
- Which finishing processes create recurring waste?
- Which subcontract charges recur?
- Which customer requirements create extra handling?
Use a meaningful sample rather than one job.
This makes the estimate more grounded without overfitting every exception.
Protect against double counting
Complex estimates can accidentally charge the same effect twice.
For example, a waste allowance may already include makeready spoilage, while another line adds setup sheets again.
A subcontract rate may include transport that is also added separately.
Review costing logic for overlap.
Accuracy is not only about adding missing cost; it is also about avoiding artificial inflation.
Distinguish cost, price and commercial strategy
Estimated cost is one input to price.
The selling price may also reflect:
- market position;
- customer relationship;
- strategic importance;
- capacity availability;
- service level;
- risk;
- order frequency.
A controlled system should allow commercial judgment without hiding the underlying cost.
Management should be able to see when price is below normal margin by deliberate choice rather than because the estimate omitted cost.
Use contribution and capacity together
A job with lower percentage margin may still make sense when it uses spare capacity efficiently.
A seemingly high-margin job can be less attractive if it consumes the plant's constrained process during a peak period.
Estimating and pricing become stronger when capacity context is visible.
This is particularly relevant in short-run and mixed-job environments where setup burden and bottleneck time matter greatly.
What management should measure
Useful indicators include:
- quoted versus actual material consumption;
- estimated versus actual setup time;
- estimated versus actual run speed;
- finishing variance;
- subcontract variance;
- jobs below expected margin;
- estimate revisions before order acceptance;
- jobs with route changes after estimation;
- repeat jobs repriced without assumption review;
- recurring variance by product family;
- customer requirements associated with repeated extra cost.
The goal is not to punish estimators.
The goal is to make the estimating model learn.
A practical monthly estimate-to-margin review
Select a small group of jobs with material variance between estimate and actual.
For each one, classify the cause:
1. specification incomplete;
2. quantity or scope changed;
3. material yield wrong;
4. setup assumption wrong;
5. run speed wrong;
6. finishing or subcontract assumption wrong;
7. production route changed;
8. execution issue;
9. rate changed;
10. deliberate commercial pricing decision.
Then decide whether the estimating standard should change.
If the cause was a one-off event, keep the standard.
If the pattern repeats, update the assumption.
ACC and Jupiter context
Jupiter is designed around printing and packaging job economics, connecting estimating, job specification, materials, production, costing, quality and delivery in one operating context. That connection makes estimate-versus-actual learning more useful because the quote and the production evidence belong to the same job history. Explore Jupiter for printing and packaging.
Use estimating confidence, not only estimated cost
Two quotations with the same expected margin can carry very different uncertainty.
A repeat carton on a stable substrate may have strong evidence. A new structure with unfamiliar finishing, outsourced foil and aggressive delivery may rely on several assumptions.
Management can treat confidence as a separate dimension.
This does not require a complex score. A simple high/medium/low confidence flag can help commercial teams identify which jobs need stronger review before commitment.
Build approval thresholds around estimate risk
High-value or low-margin estimates may deserve additional review.
So may estimates containing unusual material, new tooling, difficult subcontracting or several unresolved assumptions.
The review threshold should reflect business consequence, not merely quotation value.
This focuses senior attention on estimates where a hidden assumption could materially affect margin.
Connect estimate quality to lead-time quality
An estimate and a promised date often depend on the same assumptions.
If material lead time, press route or finishing supplier is uncertain, both cost and delivery risk increase.
Reviewing them together avoids a common problem where sales accepts an attractive margin based on a route that cannot meet the required date without expediting.
The commercial decision becomes stronger when margin and deliverability are tested against one operating plan.
Use lost-quote data carefully
Won jobs provide actual production evidence.
Lost quotes do not.
Still, they can reveal whether pricing is consistently uncompetitive in certain product families.
Do not respond by cutting price immediately.
First check whether the estimating model contains high setup, waste or subcontract assumptions that no longer reflect actual capability.
Market feedback is useful when combined with production evidence.
Make estimating ownership cross-functional
Estimators own the costing model, but many assumptions belong elsewhere.
Purchasing owns current material and subcontract information. Production understands realistic setup and run speed. Quality understands inspection requirements. Logistics understands packing and freight.
A disciplined estimating process defines how these inputs are refreshed.
That prevents one estimator from becoming the sole keeper of operational assumptions that change across the business.
Treat estimate accuracy as a management capability
Estimating quality affects more than quotation speed.
It influences which work the business wins, how much capacity is committed, what purchasing buys, what production is expected to achieve and whether margin surprises appear later.
Management should therefore review estimating performance as part of the operating model.
A strong estimating process improves commercial confidence because it connects price to the way the factory actually works.
Keep estimate review proportionate
Not every quotation needs senior review or detailed post-job analysis.
Use value, margin, novelty, uncertainty and recurring variance to decide where deeper attention is justified.
Routine jobs should move quickly.
Complex or high-risk jobs should receive stronger challenge.
That balance keeps estimating disciplined without turning speed itself into a problem.
This discipline also makes commercial decisions more explainable across teams.
Frequently asked questions
Can an estimate ever be fully accurate before production?
No. It is a controlled forecast based on known specification and assumptions. The objective is to make those assumptions realistic and visible.
Should every actual variance change the estimating standard?
No. Separate one-off exceptions from repeated evidence across similar jobs.
Is material price the biggest driver of print-job margin?
It can be important, but yield, makeready, run speed, finishing, subcontracting and waste can be equally significant depending on the job.
Should repeat jobs always use the previous actual cost?
Use prior actuals as evidence, but revalidate quantity, material, route, rates, tooling and delivery conditions.
What is the fastest way to improve estimating accuracy?
Start with jobs showing the largest recurring estimate-versus-actual variance and identify which assumption repeatedly failed.