
The Budget Matches the Tender Total. Is It Structured for Project Control?
A tender total is not yet a project-control budget. Delivery needs costs structured by work package, cost code, resource and responsibility so commitments, actuals and forecast-to-complete can be compared against the same baseline.
The short answer
A tender total can reconcile perfectly and still be a poor project-control budget.
Once delivery starts, management needs to know where the money is expected to go, what has been committed, what has actually been spent and where the project is likely to finish. That requires a structure aligned with the way the work will be managed — not just the way the estimate was originally assembled.
The strongest project budgets preserve the commercial logic of the tender while giving delivery teams a practical view of work packages, cost responsibility and forecast.
A tender total tells you what the job was priced at — not where it will move
At award, senior management often focuses on one reassuring number: the margin in the winning tender.
That number is useful, but it is not yet a control system.
Once procurement starts, different parts of the job move at different speeds. One subcontract package may be committed above budget. Another may still have no market test. Direct labour may be trending well while plant is already running high.
A single project total can hide all of this.
The budget needs enough structure to show where the economics are changing before the overall result becomes obvious.
That is why a project-control budget should be built around the places where management can actually intervene.
The delivery structure does not have to copy the estimate
Tender estimates are built to price the work. Projects are structured to deliver it.
Those are related purposes, but not identical.
An estimator may price by trade or bill item. The delivery team may prefer work packages, cost codes, zones or responsibilities. One subcontract award may combine several tender lines; one estimate line may later be delivered through several packages.
Trying to force the two structures to match exactly can create unnecessary complexity.
The better approach is to map them.
That mapping preserves the relationship to the winning tender while allowing delivery to use a structure that makes operational sense.
If the project later sees a variance, management can still ask whether the movement came from the original allowance, changed scope, procurement or execution.
Budget, commitment, actual and forecast are four different stories
These numbers are often placed in the same cost report, but they answer different questions.
Budget shows the approved baseline.
Commitment shows what has already been contracted or ordered.
Actual cost shows what has been incurred.
Forecast shows where management believes the package will finish.
A project becomes misleading when these ideas are blurred.
Early in the job, actual cost may look low simply because major packages have not yet been awarded. The budget can appear safe even though procurement is already returning quotations above allowance.
This is why expected commitment matters. If a package is likely to award above budget, management should know before the purchase order is issued.
Forecasting starts before accounting catches up.
The first quotations after award are a stress test of the tender
One of the most useful moments in project control comes when live market quotations arrive after award.
They test whether the tender allowance still reflects reality.
If several packages return above budget, the team should not immediately conclude that purchasing is underperforming. The difference may come from changed scope, quantity, specification, market movement or an estimate that relied on a narrower quotation.
The important thing is to explain the gap early.
At this stage, management may still have options: change the package boundary, negotiate scope, qualify another supplier or adjust procurement timing.
Once the award is placed, those options reduce.
A good project budget therefore interacts with procurement rather than waiting for procurement to generate actual commitments.
Contingency loses value when it becomes an invisible balancing account
Risk allowances and contingency are useful only when management knows what they are protecting.
A common weakness is to treat them as spare value that can be moved quietly to cover an overrun elsewhere.
That makes the project look healthier while destroying the original risk logic.
If a tender allowance existed for a known uncertainty, the project should be able to see when that risk materialises and how much of the allowance is consumed.
If the risk disappears, management can decide whether to release the value.
This gives the company better learning too. Future estimating improves when the business can see which risks actually converted into cost and which did not.
Forecast quality depends on who owns the remaining cost
Finance can report what has already happened. The project team usually holds the best information about what remains.
A buyer knows where supplier negotiations are moving. A project manager understands labour and plant needs. An engineer may know that a design change will affect quantity. A commercial manager can see the likely outcome of a subcontract package.
Forecasting is therefore an ownership issue as much as a system issue.
For major cost areas, someone should own the remaining-cost assumption.
The monthly review can then challenge the logic behind the forecast rather than merely compare numbers.
If the forecast has not changed despite a major programme or procurement change, that should trigger a question.
A variance is useful only if the project can explain the cause
Red and green numbers are not project control.
The useful question is what changed operationally.
Was quantity higher? Was productivity lower? Did the supplier price move? Did scope expand? Was the original allowance incomplete?
That explanation determines the action.
A procurement issue needs a different response from a productivity issue. A design change needs a different response from an estimating omission.
The project budget becomes valuable when it helps management understand cause while there is still time to react.
That is also what turns completed projects into better future tenders.
The budget also has to remain connected to the wider startup model. If the project is moving from tender win into controlled delivery, the cost structure is where many of those early assumptions become measurable.
This is particularly important when the delivery strategy changes after award. A package that was expected to be subcontracted may be brought in-house. A material may be procured directly rather than through a specialist. A sequence may be accelerated with additional plant.
Those decisions can be operationally sensible, but they change the way cost will appear. If the budget structure does not follow the new delivery model, management may interpret a planned transfer as an overrun.
A good cost baseline therefore protects two truths at the same time: what the project originally expected to spend and how the project now intends to deliver the work.
That distinction becomes increasingly valuable as the job matures. Senior management can see whether margin movement comes from the original estimate, from deliberate management decisions, from client-driven change or from execution performance.
Without that separation, project reporting tends to collapse every movement into one generic variance. The number may be accurate, but the learning is poor.
The best budgets do not simply tell management whether the job is above or below plan. They explain why.
A mature project also distinguishes between a budget problem and a timing problem. Cash may be spent earlier than expected while final cost remains unchanged, or a commitment may look adverse because one package includes scope that was previously spread elsewhere.
The cost report should help management see those differences instead of reacting to every variance as though it were the same kind of problem.
Where Epicor Saturn fits in project budgeting
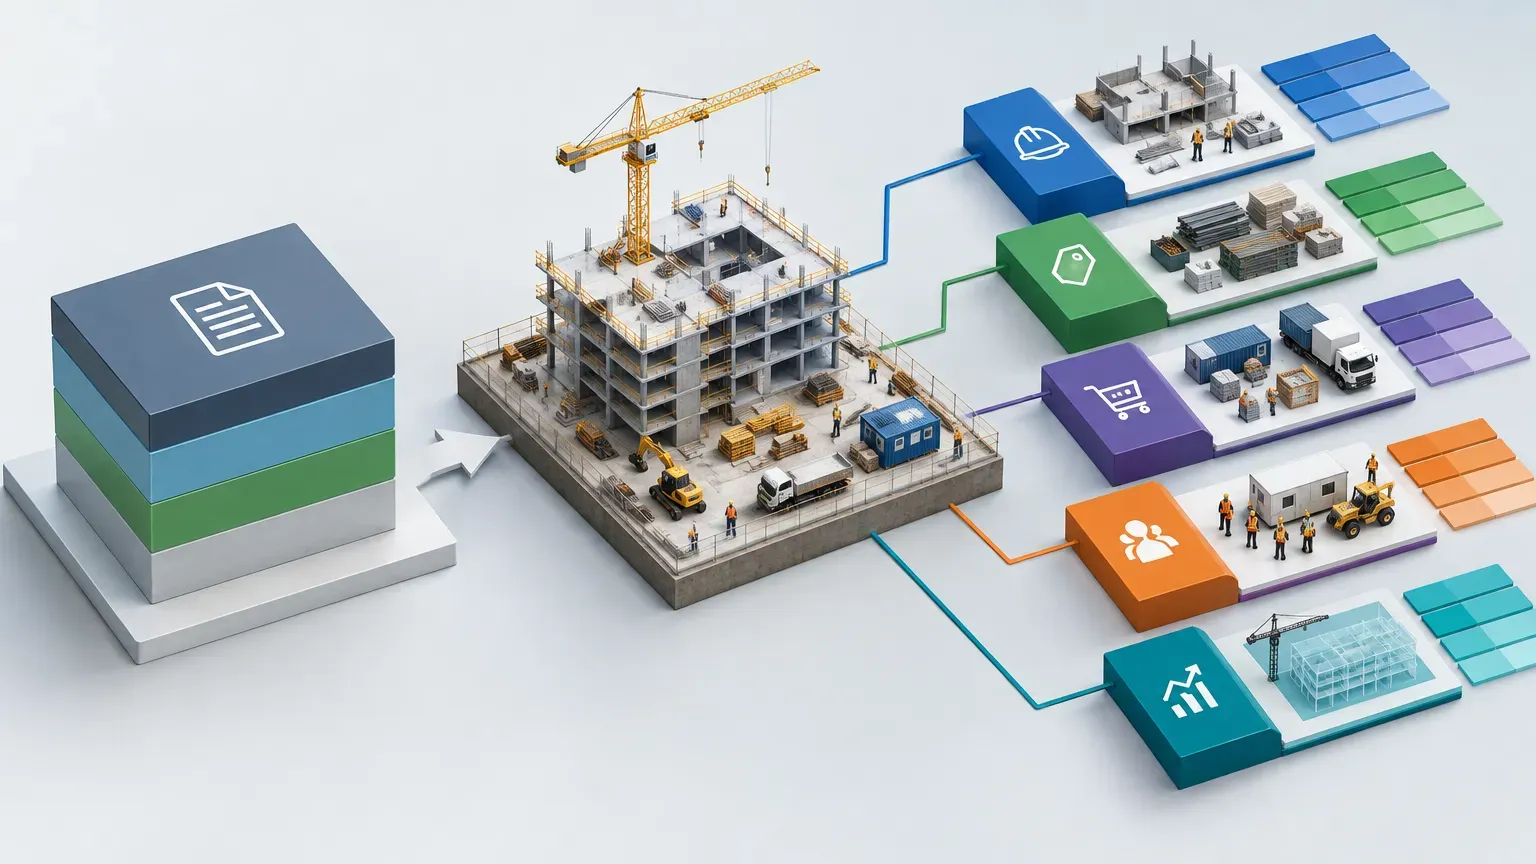
Epicor provides the enterprise-grade ERP foundation for purchasing, finance, approvals and transaction control. Epicor Saturn adds the construction and engineering industry layer that organizes those transactions around project budgets, work packages, commitments, progress and forecast.
The value is not simply that cost is recorded. It is that procurement commitments and financial actuals remain connected to the same project-control baseline that originated from the tender.
Epicor Saturn provides the project-centric industry structure while Epicor supplies the enterprise-grade financial and transactional backbone. Explore Epicor Saturn for construction and engineering.
Frequently asked questions
Should the project budget exactly match the tender estimate structure?
No. The structures can differ, but the mapping between them should remain clear.
Is committed cost the same as forecast cost?
No. Commitment covers placed obligations; forecast also includes expected remaining exposure.
When should forecasting begin?
From the start of the project, before major actual costs appear.
How much cost-code detail is enough?
Enough to support responsibility and meaningful management action without creating unnecessary transaction burden.